
Discover practical ways to manage financial stress in Nigeria, plan family expenses and explore the AYHOME Buyback Investment Scheme with MOSCOTECH REALTY LTD.
Smart Ways to Handle Economic Hardship, Daily Stress and Life’s Challenges
Learn Practical financial planning strategies for individuals, families, business owners and Nigerians in the diaspora.
MOSCOTECH REALTY LTD
Your Trusted Gateway to Profitable Real Estate Investments Back Home in Nigeria.
INVEST TODAY. PLAN FOR TOMORROW.
—
INTRODUCTION: LIVING AND THRIVING IN NIGERIA
Life in Nigeria can present significant financial challenges. Rising living costs, housing expenses, children’s school fees, transportation, healthcare, business obligations and other responsibilities can place pressure on individuals and families.
For salaried employees, civil servants, entrepreneurs, business owners and Nigerians living abroad who support relatives at home, managing money effectively is an important part of everyday life.
When financial responsibilities exceed available resources, the resulting stress can affect sleep, relationships, concentration and general well-being. Chronic stress may also contribute to high blood pressure, although hypertension has several possible causes and requires appropriate medical assessment.
The solution is not simply to work harder. It is to develop practical strategies for managing expenses, protecting your well-being, building savings and making informed financial decisions.
At MOSCOTECH REALTY LTD, we recognise the importance of financial planning and invite individuals, families and organisations to explore suitable real estate investment opportunities as part of their broader financial goals.
Remember: Your health matters. Your peace of mind matters. Your financial future matters.
1. UNDERSTAND YOUR FINANCIAL PRESSURES
Before making an investment decision, identify the financial obligations placing the greatest pressure on your income.
These may include:
– Monthly rent and housing expenses.
– Children’s school fees and educational costs.
– Food, transportation and utility bills.
– Healthcare and family support.
– Business expenses and debt repayments.
– Financial support for relatives in Nigeria or abroad.
– Retirement planning and long-term savings.
Write down your regular income, essential expenses, outstanding debts and savings. This will help you determine what you can realistically afford to save or invest without compromising your immediate needs.
2. CREATE A PRACTICAL FINANCIAL PLAN
A financial plan should reflect your actual circumstances rather than unrealistic expectations.
Consider these steps:
Set priorities. Provide for essential household expenses before committing money to an investment.
Build an emergency reserve. Where possible, maintain accessible savings for unexpected expenses.
Manage debt carefully. Understand interest rates, repayment dates and penalties before taking on additional borrowing.
Avoid unnecessary spending. Review recurring subscriptions, impulse purchases and other expenses that can be reduced.
Plan ahead. Prepare for annual rent, school fees, healthcare expenses and other foreseeable commitments before they become urgent.
Review your progress. Revisit your budget regularly and adjust it when your income or circumstances change.
A good financial plan should reduce uncertainty, not introduce additional pressure.
3. PROTECT YOUR HEALTH WHILE MANAGING FINANCIAL STRESS
Financial success should never come at the expense of your health.
Practical steps for managing stress include:
– Maintain a consistent sleep routine.
– Engage in regular physical activity suited to your abilities.
– Eat a balanced diet and limit excessive salt intake.
– Make time for relaxation, family and supportive relationships.
– Avoid using alcohol or unprescribed medication to cope with stress.
– Check your blood pressure and seek medical advice when appropriate.
High blood pressure often has no obvious symptoms. Do not rely on how you feel to determine whether your blood pressure is normal. Arrange appropriate checks with a qualified healthcare professional.
If financial anxiety becomes overwhelming, consider speaking with a trusted person or a qualified mental health professional.
4. YOUR SALARY SHOULD NOT BE YOUR ONLY FINANCIAL PLAN
For many Nigerians, salary or business income must cover several competing obligations. Although earning a regular income is important, financial resilience can also involve budgeting, emergency savings, debt management and suitable long-term investments.
The key is to understand how each financial decision affects your present needs and future goals.
For individuals with genuinely surplus funds, a carefully assessed investment may form part of a broader financial strategy. However, investments involve risks, and no investment should be funded with money needed for immediate living expenses.
This brings us to an investment opportunity marketed by MOSCOTECH REALTY LTD.
5. EXPLORE THE AYHOME CONTRACTUAL BUYBACK INVESTMENT SCHEME
Invest Today. Plan for Tomorrow.
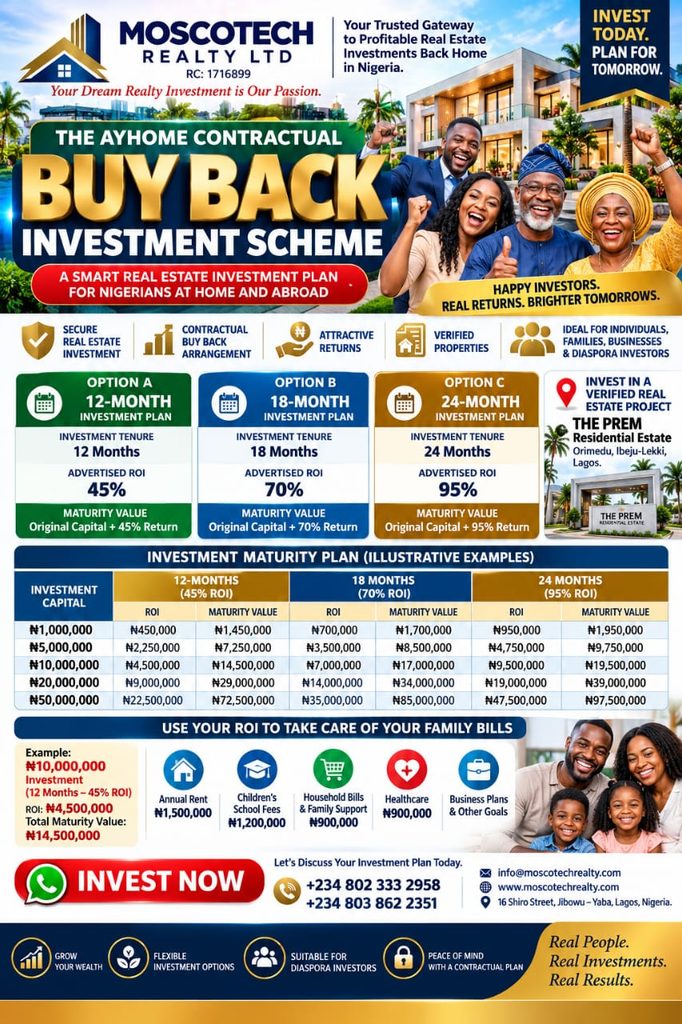
The AYHOME Contractual Buyback Investment Scheme is marketed by MOSCOTECH REALTY LTD and is associated with THE PREM Residential Estate, Orimedu, Ibeju-Lekki, Lagos.
The scheme presents three advertised investment options with different tenures and stated returns. Prospective investors should examine the contractual structure, the responsible parties, the property documentation, the buyback arrangements and the applicable bond before making a commitment.
The advertised investment options begin at ₦1 million.
6. WHO MAY CONSIDER THE INVESTMENT PLAN?
The scheme may be of interest to individuals and eligible organisations evaluating real estate-related investment opportunities.
Corporate employees: Professionals who want to consider investment options alongside their regular employment income.
Civil servants: Public-sector employees planning for future housing, education, retirement and other commitments.
Business owners and entrepreneurs: Individuals assessing whether surplus business or personal capital can be committed for an agreed period.
Families: Parents and households planning ahead for significant expenses.
Nigerians in the diaspora: Nigerians abroad exploring investment opportunities in their home country.
Corporate organisations: Eligible organisations assessing potential investments in line with their treasury policies, cash-flow needs and due-diligence requirements.
Eligibility and suitability depend on the applicable investment terms and the investor’s individual circumstances.
7. UNDERSTAND THE THREE INVESTMENT OPTIONS
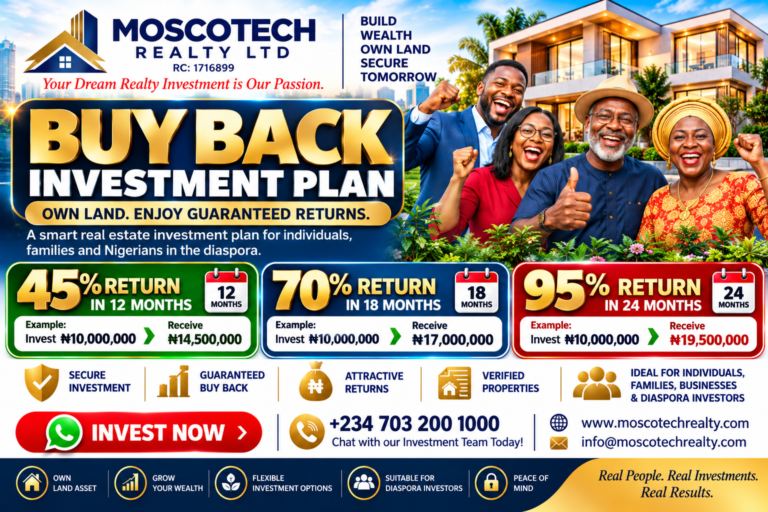
The following percentages are the advertised total returns for each complete investment tenure. They are not monthly returns.
Option A: 12-Month Investment Plan
– Investment tenure: 12 months.
– Advertised ROI: 45%.
– Illustrative maturity value: Original capital plus 45% ROI.
Option B: 18-Month Investment Plan
– Investment tenure: 18 months.
– Advertised ROI: 70%.
– Illustrative maturity value: Original capital plus 70% ROI.
Option C: 24-Month Investment Plan
– Investment tenure: 24 months.
– Advertised ROI: 95%.
– Illustrative maturity value: Original capital plus 95% ROI.
The actual payment obligations, maturity dates and repayment arrangements must be established by the applicable signed investment agreement.
8. INVESTMENT RETURNS AND MATURITY VALUES
The table below illustrates the calculations using the advertised total ROI percentages.
Investment capital| 12-month ROI (45%)| 12-month maturity| 18-month ROI (70%)| 18-month maturity| 24-month ROI (95%)| 24-month maturity
₦1,000,000| ₦450,000| ₦1,450,000| ₦700,000| ₦1,700,000| ₦950,000| ₦1,950,000
₦5,000,000| ₦2,250,000| ₦7,250,000| ₦3,500,000| ₦8,500,000| ₦4,750,000| ₦9,750,000
₦10,000,000| ₦4,500,000| ₦14,500,000| ₦7,000,000| ₦17,000,000| ₦9,500,000| ₦19,500,000
₦20,000,000| ₦9,000,000| ₦29,000,000| ₦14,000,000| ₦34,000,000| ₦19,000,000| ₦39,000,000
₦50,000,000| ₦22,500,000| ₦72,500,000| ₦35,000,000| ₦85,000,000| ₦47,500,000| ₦97,500,000
How the calculation works
For the 12-month option:
– Original investment: ₦10,000,000.
– Advertised ROI: 45% of ₦10,000,000 = ₦4,500,000.
– Illustrative total maturity value: ₦10,000,000 + ₦4,500,000 = ₦14,500,000.
These are mathematical illustrations based on the stated percentages, not independent verification that the returns or principal repayment will be achieved. The signed agreement and applicable law govern the actual arrangement.
9. HOW INVESTMENT RETURNS MAY FIT INTO A FAMILY BUDGET
Consider a hypothetical household investing ₦10 million under the 12-month option.
If the advertised 45% ROI were paid in full, the illustrative return would be ₦4.5 million.
The family might plan its use as follows:
Planned expense| Illustrative allocation
Annual rental accommodation| ₦1,500,000
Children’s school fees| ₦1,200,000
Household bills and family support| ₦900,000
Reserve for future commitments| ₦900,000
Total planned allocation| ₦4,500,000
This example demonstrates how a prospective investment return could be incorporated into a household budget. It is not a guarantee of payment or a recommendation that every family should invest ₦10 million.
The timing of expenses must match the contractual payment schedule. If the return is payable only at maturity, investors should not rely on receiving it earlier to meet monthly bills.
Investors should also consider the possibility of delayed or missed payments, inflation, taxes, transaction costs and the loss of some or all of their capital.
10. WHAT SHOULD YOU VERIFY BEFORE INVESTING?
The AYHOME Buyback Investment plan is presented with a commitment to honour the agreed investment terms. Any protection, security or repayment obligation depends on the signed agreement, the enforceability of the relevant documents and the ability of the responsible parties to perform their obligations.
– The complete investment agreement.
– The legal identity and responsibilities of every contracting party.
– The relevant property title and verification documents.
– The precise buyback terms, maturity dates and payment arrangements.
– A deed of buyback or repurchase document and the specific obligations it creates.
– Any bond, guarantee or other security document, including its issuer, scope, validity and enforcement process.
– A post-dated cheque provided on request, as a guaranteed .
– A written acknowledgement and receipt confirming the funds received, the investment terms and the applicable maturity date.
– The legal and regulatory status of the arrangements.
A deed, bond, post-dated cheque on request.
An acknowledgement letter which provide evidence of the parties’ stated obligations,
To support transparency and effective planning, approximately two weeks before an investment reaches maturity, the client will receive an email notification confirming the maturity date and asking whether they wish to roll over the investment or cash out. Based on the investor’s instruction, the funds will be processed accordingly.
11. WHY CONSIDER MOSCOTECH REALTY LTD?
MOSCOTECH REALTY LTD is a Nigerian real estate marketing and investment advisory company focused on helping individuals, families, organisations and Nigerians in the diaspora explore property-related opportunities.
Our stated mission is to provide prospective investors with information that supports informed property and investment decisions.
We encourage clients to ask questions, request for investment video, FAQ and application form for more insightful information.
Your Dream Realty Investment is Our Passion.
12. TAKE A STEP TOWARDS BETTER FINANCIAL PLANNING
You work hard for your money. Your financial decisions deserve careful thought, proper documentation and a clear understanding of the investment potential and return on investment.
Whether you are a salaried employee, civil servant, business owner, parent, corporate executive or Nigerian living abroad, start by understanding your financial position and defining your goals.
If you would like more information about the AYHOME Buyback Investment Scheme, contact MOSCOTECH REALTY LTD to request the relevant investment details and supporting documentation.
INVEST TODAY. PLAN FOR TOMORROW.
CONTACT MOSCOTECH REALTY LTD
MOSCOTECH REALTY LTD
Your Trusted Gateway to Profitable Real Estate Investments Back Home in Nigeria.
– Telephone: +234 802 333 2958
– Telephone: +234 803 862 2351
– WhatsApp: “Chat with our team” (https://wa.me/2348023332958)
– Email: info@moscotechrealty.com
– Website: “https://moscotechrealty.com” (https://moscotechrealty.com)
– Office: 16 Shiro Street, Jibowu–Yaba, Lagos, Nigeria.
Your Dream Realty Investment is Our Passion.
.